
Picture this. You own a UAE parent company with three subsidiaries. One turns a healthy profit. Another is losing money. The third sits somewhere in between.
Someone on your finance team suggests forming a Tax Group. Sounds simple enough, right?
Not quite. Getting corporate tax compliance UAE right means asking a harder question first. Will grouping these companies actually improve your tax position? Or will it just complicate things?
The answer depends on your numbers. Not the number of entities you own.
Tax Grouping touches your taxable profits. It touches the AED 375,000 threshold. It touches Small Business Relief, existing losses, intra-group transactions, and liability across the group. Get it right, and you simplify your structure. Get it wrong, and you lose reliefs you didn’t realise were at risk.
What Does Tax Grouping Actually Mean?
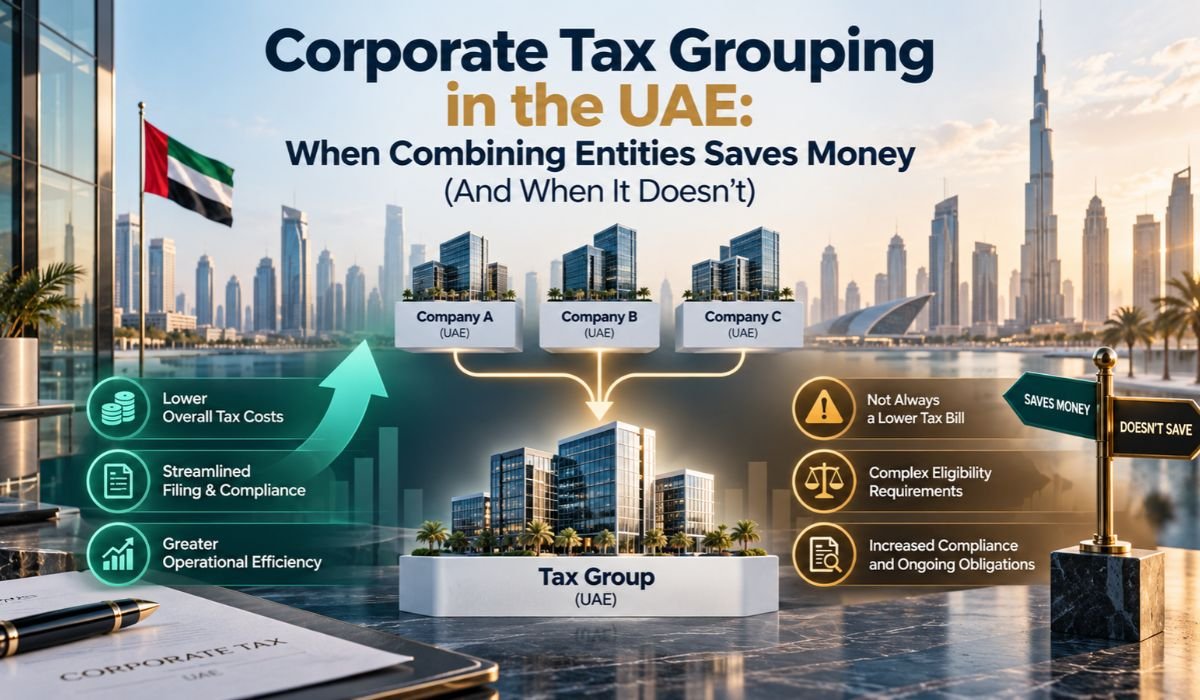
A UAE Tax Group lets eligible companies elect to be treated as one taxable person. The parent typically handles filing. The group submits a single Corporate Tax return instead of several.
To qualify, companies generally need a parent-subsidiary relationship. That means at least 95% ownership, covering voting rights and entitlement to profits and assets. UAE residency and other eligibility conditions apply too.
Not everyone qualifies, though. Exempt persons face restrictions. So do entities that fail the ownership test. Qualifying Free Zone Persons (QFZPs) face their own set of complications, worth checking before you assume grouping is even possible.
When Does Grouping Actually Save Money?
Here’s the principle. Grouping helps when combining your taxable results produces a better outcome than filing separately ever could.
Profit meets loss. Say Company A earns AED 800,000. Company B loses AED 300,000. Filed separately, A pays tax on its full profit while B’s loss sits unused. Grouped, the combined taxable income drops to AED 500,000. That’s real money.
Heavy intra-group trading. Do your companies constantly invoice each other for management fees or shared services? Grouping can simplify how those transactions get treated. They’re generally eliminated at group level.
Administrative relief. One return instead of three or four sounds appealing. It can genuinely cut the workload for a straightforward group. Just don’t assume this holds true once the structure gets complicated. It doesn’t always.
When Does Grouping Cost You Instead?
This is the part most articles skip past. Grouping isn’t free money.
The threshold shrinks. Separately, each company gets its own AED 375,000 tax-free threshold. Group two profitable companies together, though, and you get one threshold for the whole group.
| Scenario | Company A | Company B | Tax Treatment |
| Filed separately | AED 500,000 taxable | AED 500,000 taxable | Two thresholds applied |
| Filed as a Tax Group | AED 1,000,000 combined | — | One threshold applied |
Two profitable companies just lost a threshold they’d have kept apart. That’s not a small detail. It’s the whole decision.
Small Business Relief gets complicated too. If either company currently qualifies, or hopes to, grouping changes how revenue gets assessed. Model this before you commit. Not after.
What Happens to Existing Losses?
Losses generated after joining the group behave straightforwardly. Pre-grouping losses don’t.
A company’s losses from before it joined generally can’t just merge into one shared pool. Restrictions apply. These are often tied to that specific company’s own taxable income going forward. One company’s losses can offset another’s profits. But only under defined conditions, not automatically.
Leave the group later, and things get trickier still. Pre-grouping losses and group-generated losses get treated differently. This is exactly why planning an exit matters as much as planning entry.
One thing worth remembering: Tax Grouping is not the same mechanism as the 75% loss-transfer rules or Qualifying Group relief. Businesses often assume these are interchangeable. They’re not.
Tax Group vs Separate Filing
| Area | Separate Entities | Tax Group |
| Taxable person | Each entity | Group as one |
| Tax return | Multiple | Single |
| AED 375,000 threshold | Applied per entity | Applied once, group-wide |
| Profits/losses | Kept separate | Consolidated, with conditions |
| Liability | Entity-level | Joint and several |
Separate filing tends to make more sense in a few situations. Several companies are independently profitable. A QFZP is involved. Or you’re planning to sell a subsidiary soon. None of these rule out grouping entirely. They just mean you should run the numbers first.
What About Free Zone Companies?
Here’s a common misunderstanding. Having a Free Zone licence doesn’t automatically mean QFZP status. The two get confused constantly.
If a QFZP joins a Tax Group, it risks losing that 0% regime treatment altogether. A mainland parent with a Free Zone subsidiary needs to check this interaction carefully. Do it before filing an election. Unwinding it afterward is far messier than checking beforehand.
Does One Return Mean Less Work?
Not necessarily. You’ll still need financial data from every member. Group-level adjustments. Loss tracking. Records covering any membership changes.
Larger groups may also need audited special-purpose aggregated financial statements. That’s a cost worth factoring into your decision. Not an afterthought.
The Liability Question Nobody Asks Early Enough
If one group member runs into a Corporate Tax problem, can the others be affected? Generally, yes.
Joint and several liability means the parent and members can carry exposure across the group. Not just individually. This matters enormously when you’re acquiring a company. Bringing an unknown tax history into your group brings its risks in with it.
Five Numbers to Calculate Before You Apply
- Combined taxable income across the group
- What each company would owe filed separately
- How the AED 375,000 threshold shifts at group level
- Which losses are pre-grouping versus post-grouping
- Whether Small Business Relief or QFZP status is at risk
Skip this exercise, and you’re guessing. Do it, and the decision usually becomes obvious.
Keeping Compliance Under Control After Grouping
Strong corporate tax compliance UAE practice doesn’t end once you’ve filed the election. Keep ownership records current. Track pre-grouping losses separately from day one. Reconcile intercompany balances regularly.
Monitor QFZP status and ownership percentages continuously. Dropping below 95% changes everything. Review the structure again before any acquisition or disposal, rather than after.
Frequently Asked Questions
Does forming a UAE Tax Group always reduce Corporate Tax?
No, it depends entirely on your specific numbers. Grouping helps when profits and losses sit together within the structure. Two profitable companies can actually end up worse off after losing their separate thresholds.
Can a profitable company and a loss-making company form a Tax Group?
Yes, and this combination often produces the clearest tax benefit available. The loss offsets the group’s combined taxable income immediately. This is usually the strongest case for grouping in the first place.
Can a QFZP join a UAE Tax Group?
It’s technically possible, but doing so risks the QFZP’s valuable 0% tax treatment. That interaction needs careful review before filing anything. Once the election goes in, reversing it becomes far more complicated.
What happens to losses that existed before a company joined the group?
Pre-grouping losses don’t simply merge into one shared group pool. Restrictions apply, often tied to that company’s own future taxable income. This is a detail many businesses overlook until it costs them.
What happens if a company later leaves the Tax Group?
Pre-grouping losses and group-generated losses get treated differently once a company exits. This is exactly why planning an exit matters as much as planning entry. Ignoring it now often creates problems down the line.
Conclusion
Grouping is a structural decision, not a filing shortcut. The right comparison weighs tax saved against tax potentially lost. It also weighs the compliance and liability trade-offs that come with it. What works brilliantly for one group can backfire for another with almost identical numbers.
Model your own figures before applying. And if the calculations feel more complex than a spreadsheet can comfortably handle, that’s usually the moment to bring in someone who does this daily. Before the election gets filed. Not after.
At Dubai Business & Tax Advisors (DBTA), that’s exactly the kind of groundwork we help businesses get right from the start.
 Qamer Javed